Credit History in Poland: How to Prepare for a Car or Home Loan
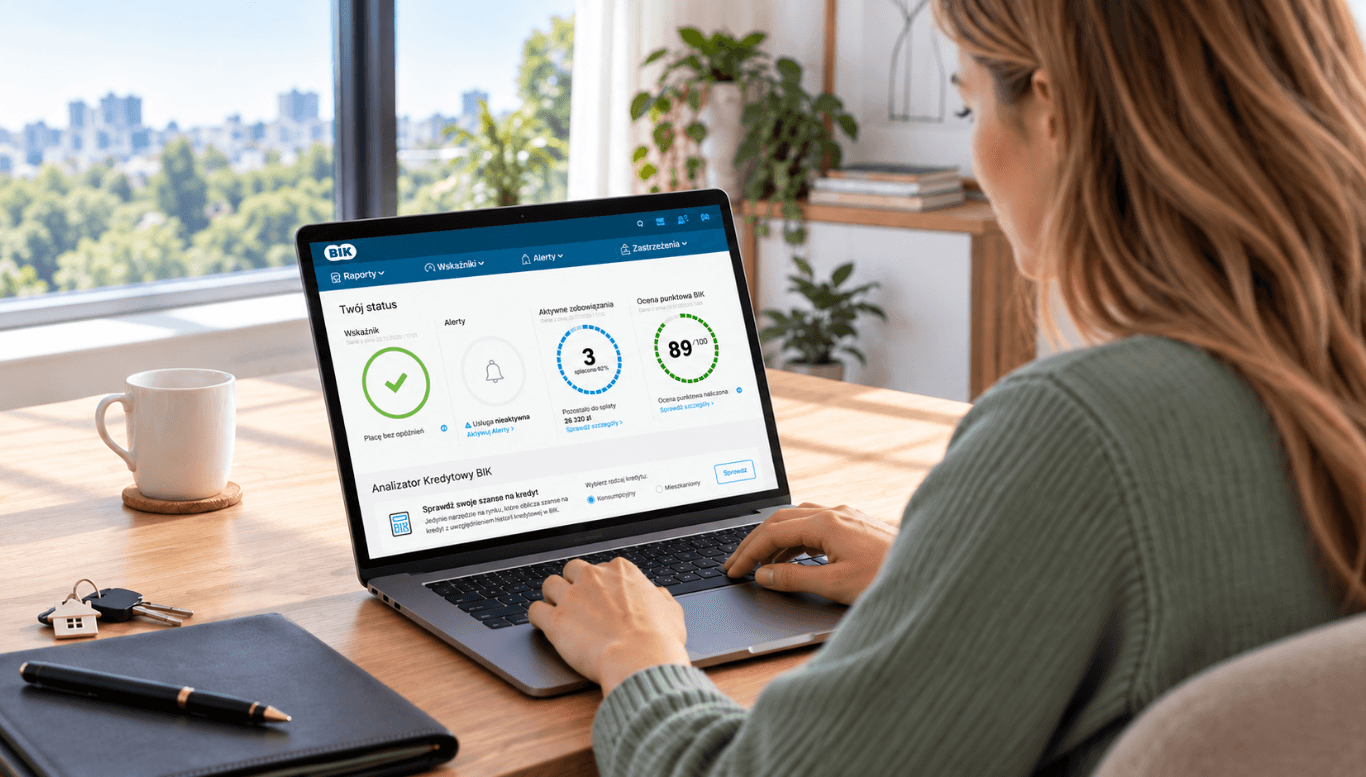 Are you working in Poland, earning a stable income and considering a loan for a car or property? According to BIK data, in the first half of 2026 as many as 364,000 foreign nationals held loans and credit products, with Ukrainian citizens accounting for 56% of the value of this credit portfolio.
For a bank, however, a stable income may not be enough. When reviewing an application, it examines not only the salary and contract, but also how the person has used credit in the past and whether they have repaid their obligations on time.
It is therefore better to prepare for a major loan well in advance.
What BIK Is and How It Works
BIK (Biuro Informacji Kredytowej) is the largest credit data register in Poland. It collects information on the credit obligations of customers of banks and other authorised financial institutions, operating on the basis of Article 105, paragraph 4 of the Banking Law Act. BIK cooperates with all commercial and cooperative banks in Poland.
The register holds information on active loans and credits, outstanding amounts, payment history and any arrears. According to BIK data, over 90% of the information in the database relates to obligations being repaid in a timely manner.
On the basis of credit history, BIK calculates a scoring - a numerical rating from 1 to 100. The higher the score, the greater the probability of timely loan repayment in BIK's assessment. There is, however, no single threshold score above which a loan is guaranteed to be approved: each bank applies its own assessment criteria.
In 2026, BIK began implementing a new scoring model that takes into account, among other things, data from the loans and deferred payments sector.
BIK does not make lending decisions. The final decision always rests with the bank, which applies its own customer assessment rules.
What the Absence of a Credit History Means
The absence of entries in the register does not mean a poor credit history and is not in itself grounds for refusal. If you have not previously used credit products in Poland, BIK may simply not have sufficient information to calculate a scoring.
If there is no credit history at all, it is possible to start building one. According to BIK data, a scoring can begin to form after six months of timely repayment of a loan or credit facility of at least PLN 400. Using a credit limit over a sufficient period of time may also be relevant.
It is precisely the timely repayment of obligations that gradually builds a positive credit history. If you are using a loan, a credit card or another product recorded with BIK, it is important to make payments on time and avoid arrears.
That said, there is no need to take out an unnecessary loan simply to appear in the BIK database. If you do not yet have a credit history, it is worth first checking the requirements of the bank at which you plan to apply and establishing whether the absence of a scoring will actually be a problem in your specific situation.
How a Bank Assesses a Foreign National
For a Ukrainian national, credit history with BIK is only one part of the verification process. The bank also assesses residence status, income, the form and stability of employment, current obligations, and - in the case of a mortgage - the size of the down payment.
The requirements regarding the document confirming the right to reside in Poland, length of employment and the set of documents required vary depending on the bank and the type of loan. It is therefore necessary to check the conditions of the specific institution before submitting an application.
If entries exist in BIK, the bank examines them in detail. Timely repayments and closed obligations can positively influence the assessment of an application, whereas arrears or unpaid debts may adversely affect the credit history.
Under a umowa o pracę or umowa zlecenia, the bank may request: confirmation of residence status, a PESEL number, a Polish bank account, a zaświadczenie o zatrudnieniu (employment certificate), a PIT-11 form and bank statements for the past few months.
Under a JDG or B2B arrangement, the following may additionally be required: an annual PIT tax declaration in the form corresponding to the applicable taxation regime, bank statements, confirmation of ZUS contribution payments and a certificate from the tax office confirming the absence of arrears.
For a mortgage, the requirements are generally stricter and should be verified directly before submitting an application.
How to Check Your Credit History with BIK
Check your data with BIK. Go to bik.pl and register an account. Once every 6 months you can obtain a free copy of your data - the waiting period is up to 30 days. A paid report costs PLN 59 and is available immediately.
Verify the accuracy of the entries. If there are entries in the database, check each one. If you find incorrect or outdated information, contact the bank or other financial institution that submitted the data to BIK.
Check whether your credit history is already being built. If you are already using a loan, an instalment plan or a credit card, make your payments on time. If you do not yet have a credit history, bear in mind that BIK requires a certain period of credit activity before it can generate a scoring.
Prepare your documents in advance. The absence of even a single document may result in refusal before BIK verification even takes place.
What to Know Before Submitting an Application
Before approaching a bank, check: whether the institution considers applications from Ukrainian nationals with your type of document, what minimum length of employment and form of contract it requires, and whether it takes into account income from a umowa zlecenia or JDG.
Credit history with BIK is an important element of verification, but not the only factor. Even a good scoring does not guarantee approval.
The bank separately assesses creditworthiness: income stability, form of employment, current loans and other financial obligations. In the case of a mortgage, the size of the down payment and the document requirements for foreign nationals are additionally significant. For a car loan, the specific conditions depend on the bank's policy.
Before submitting an application, it is therefore important to check not only your BIK record, but also the requirements of the specific bank in relation to your situation.
An official contract and confirmed income are part of the same overall picture that the bank assesses alongside credit history.
Job vacancies across Poland and Europe, official employment, support at every stage. To find a vacancy, call: +380 50 334 93 51, +48 525 275 003.


 2026-11-03

 View

